

The creator economy is no longer one market.
It is a stack of related business models: talent representation, creator-led media, podcast networks, social commerce, influencer marketing software, live shopping, music rights and content licensing.
That is what made the recent activity notable. Buyers and investors were not just chasing creators as personalities. They were backing infrastructure, distribution, monetization rights, agency capability and commerce outcomes.
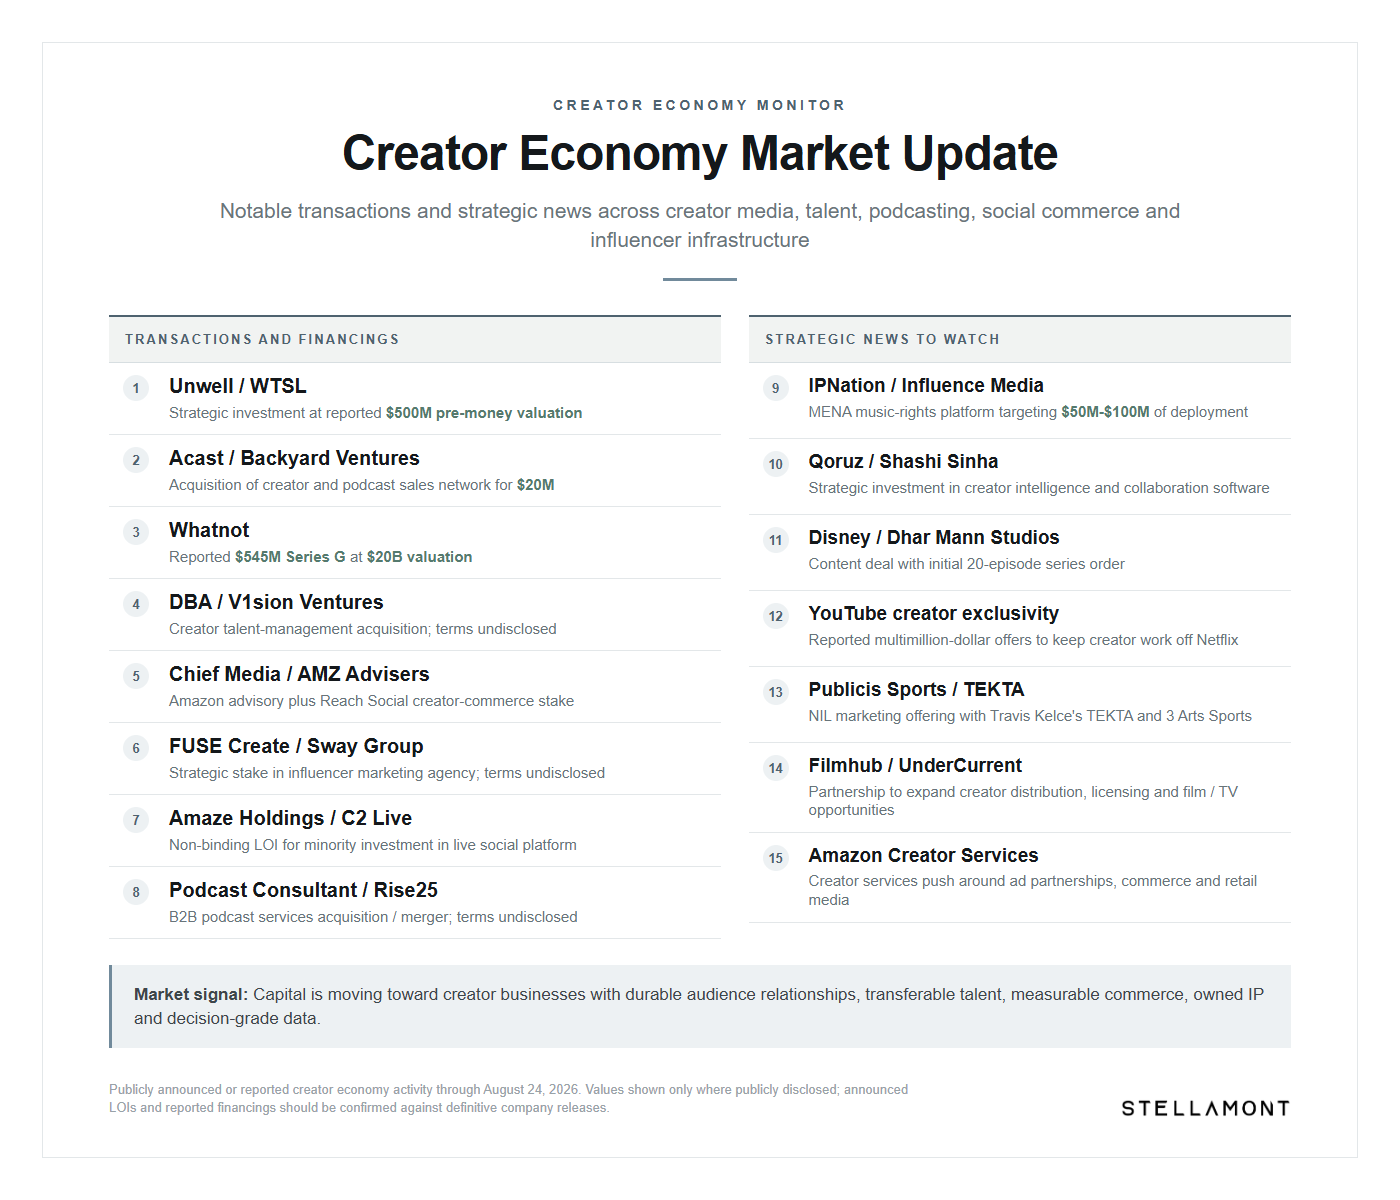
Below are the most notable publicly reported transactions and strategic announcements from the period, and what each one says about where capital is moving.
1. Unwell secured outside investment at a reported $500 million pre-money valuation
Company: Unwell
Investor: WTSL
Structure: Strategic minority investment
Valuation: Reported $500 million pre-money
Investment amount: Not disclosed
Unwell, the media company co-founded by Alex Cooper and Matt Kaplan, secured its first outside capital from WTSL, the investment firm led by former Endeavor executives Patrick Whitesell and Jason Lublin.
The headline number is the reported $500 million pre-money valuation. The investment amount and ownership percentage were not disclosed.
Unwell is important because it is not just a podcast company. Public reporting describes a platform spanning podcasts, video, live events, production, consumer products and brand work. That makes it a useful valuation marker for scaled creator-led media businesses that can extend audience into multiple revenue streams.
For buyers, the key diligence questions are not limited to downloads or followers. They include audience durability, host concentration, owned IP, ad revenue quality, renewal behavior, margin profile and the ability to monetize the same audience across audio, video, live, licensing and commerce.
2. Acast acquired Backyard Ventures for $20 million
Buyer: Acast
Target: Backyard Ventures
Structure: Acquisition
Consideration: $20 million
Acast acquired Backyard Ventures, a U.S. creator and podcast sales network, for total consideration of $20 million, including $16 million in cash at closing and $4 million in deferred Acast shares.
Backyard Ventures brought more than 200 creators across audio, YouTube, newsletters and social. Acast also disclosed that Backyard generated $16.1 million of revenue in 2025 with a 12 percent adjusted EBITDA margin.
The strategic logic is straightforward. Podcast companies are increasingly trying to sell creator inventory across more than one channel. Audio alone is not enough. Advertisers want omnichannel creator reach, measurable campaigns and bundled inventory across podcasts, YouTube, newsletters and social.
This transaction is one of the cleaner examples of the creator economy moving from personality-led media to packaged, sellable, multi-format advertising inventory.
3. Digital Brand Architects acquired V1sion Ventures
Buyer: Digital Brand Architects
Target: V1sion Ventures
Structure: Acquisition
Consideration: Not disclosed
Digital Brand Architects, the creator talent-management and influencer marketing business owned by UTA, acquired V1sion Ventures, a boutique creator talent-management firm founded by Alina Benun.
V1sion Ventures was founded in 2022 and focuses on creator representation, brand development and commercial partnerships. Benun and the V1sion team joined DBA as part of the transaction.
The transaction reinforces a continued consolidation theme in creator representation. Talent management remains fragmented, and buyers can use acquisitions to add creator rosters, manager relationships and category depth.
The diligence question is always retention. The value is tied to whether creators and managers stay after closing, whether contracts transfer cleanly, and whether the buyer can expand commercial opportunities without disrupting the creator relationship.
4. Chief Media acquired AMZ Advisers and AMZ Advisers’ stake in Reach Social
Buyer: Chief Media
Target: AMZ Advisers / Reach Social stake
Structure: Acquisition
Consideration: Not disclosed
Chief Media acquired AMZ Advisers and AMZ Advisers’ stake in Reach Social, a creator-led social commerce agency focused on TikTok Shop and retail-platform growth.
This is a social commerce capability acquisition. AMZ Advisers brings Amazon marketplace expertise, while Reach Social adds creator-led commerce and TikTok Shop capability.
The strategic rationale reflects a broader shift in the market. Brands do not just want influencer impressions. They want measurable commerce outcomes. Agencies that can connect creators, marketplace operations and retail conversion are likely to become more valuable as creator budgets move closer to performance marketing and retail media.
5. FUSE Create acquired a strategic stake in Sway Group
Investor: FUSE Create
Company: Sway Group
Structure: Strategic investment
Consideration: Not disclosed
FUSE Create acquired a strategic stake in Sway Group, an influencer marketing agency. Sway will remain independent and certified woman-owned.
This is not a full integration story. It is a strategic stake that gives Sway access to deeper creative strategy, PR, paid media and integrated campaign resources while preserving the identity and certification status of the business.
That structure is worth noting. In influencer marketing services, full acquisitions can create integration risk. Strategic stakes can give both sides commercial leverage without forcing a complete operating merger on day one.
6. Whatnot reportedly raised $545 million at a $20 billion valuation
Company: Whatnot
Structure: Series G financing
Capital raised: Reported $545 million
Valuation: Reported $20 billion
Live-shopping marketplace Whatnot reportedly raised $545 million at a $20 billion valuation.
Whatnot combines marketplace infrastructure with live video, community and creator-led selling. Sellers host live broadcasts, interact with buyers and convert entertainment and expertise into real-time commerce.
The reported valuation matters because it highlights the strategic value of owning the transaction layer. Media companies monetize attention through ads and sponsorships. Commerce platforms can monetize the purchase itself.
That distinction is relevant across the creator economy. Businesses that can connect creator influence directly to GMV or attributable sales may command stronger interest than businesses that only measure impressions or engagement.
7. Amaze Holdings signed a non-binding LOI to invest in C2 Live
Investor: Amaze Holdings
Target: C2 Live
Structure: Strategic minority investment
Status: Announced LOI, not closed
Amaze Holdings entered into a non-binding letter of intent to make a strategic minority investment in C2 Live, a creator-first live social platform.
Because this is an LOI, it should be treated as announced and pending rather than closed. Still, it belongs on the watch list because it points to continued investor interest in creator monetization infrastructure, live social engagement and social commerce.
The creator economy has always had an attention problem and a monetization problem. Platforms like C2 Live sit in the middle: they try to give creators a more direct way to turn live audience engagement into commercial value.
8. The Podcast Consultant acquired Rise25
Buyer: The Podcast Consultant
Target: Rise25
Structure: Acquisition / merger
Consideration: Not disclosed
The Podcast Consultant acquired / merged with Rise25, a done-for-you B2B podcasting service. Dr. Jeremy Weisz will remain involved as Director of Client Success.
This is smaller than the Acast / Backyard transaction, but it points to the same direction: podcasting is becoming a services, content and distribution category with enough recurring client demand to support consolidation.
For B2B companies, podcasts increasingly function as relationship infrastructure. They create content, but they also create a reason to build executive relationships, support outbound sales and develop owned media. That makes podcast production and strategy attractive to buyers looking for recurring marketing-services revenue.
9. IPNation and Influence Media Partners launched a MENA music-rights investment platform
Platform: IPNation
Strategic partner: Influence Media Partners
Structure: Music and entertainment IP investment platform
Target deployment: $50 million to $100 million
IPNation and Influence Media Partners announced a platform dedicated to music and entertainment intellectual property across the Middle East and North Africa.
The platform is targeting $50 million to $100 million of deployment across approximately 10 to 20 catalog transactions, with expected individual ticket sizes ranging from $2 million to $10 million.
The strategy includes master recordings, publishing rights and name, image and likeness rights. It also reflects a broader trend: creator-owned and artist-owned intellectual property is becoming an institutional asset class.
For creators and rights holders, this widens the liquidity menu. A transaction does not have to be a full exit. Rights owners can sell a majority stake, sell a minority stake or structure partial liquidity while retaining participation in future upside.
10. Shashi Sinha invested in creator-intelligence platform Qoruz
Investor: Shashi Sinha
Company: Qoruz
Structure: Strategic investment
Investment amount: Not disclosed
Former Omnicom Media India strategic advisor Shashi Sinha invested in Qoruz, an India-based influencer marketing and creator-intelligence platform.
Qoruz provides tools for creator discovery, audience analysis, campaign planning, outreach, competitor monitoring and performance reporting. The investment amount was not disclosed.
The transaction reflects continued demand for creator marketing infrastructure. As brand budgets grow, marketers need more than a spreadsheet of influencers. They need workflow tools, verified data, brand-fit analysis, performance measurement and repeatable campaign management.
Platforms embedded in those workflows may benefit from recurring revenue and valuable campaign-level data.
Other notable strategic announcements
Not every important item was an M&A transaction or financing. Several announcements during the period still matter because they show where the market is moving.
Disney signed a content deal with Dhar Mann Studios
Disney signed a content deal with Dhar Mann Studios, including an initial 20-episode series order. This is a clear signal that traditional media buyers continue to license and package scaled creator studio output directly.
YouTube reportedly offered creators multimillion-dollar exclusivity packages
YouTube reportedly offered top creators multimillion-dollar incentives to keep their work off Netflix. These are not reported M&A transactions, but they matter because they show platforms using exclusivity economics to defend premium creator content.
Publicis Sports and Travis Kelce’s TEKTA launched an NIL marketing offering
Publicis Sports and Travis Kelce’s TEKTA announced an NIL-focused marketing offering, with 3 Arts Sports as a strategic operating partner. The announcement shows holding companies turning creator and athlete activation into a more formal product for large brand clients.
Filmhub partnered with UnderCurrent
Filmhub announced a partnership with talent-management company UnderCurrent to help digital creators expand into distribution, licensing and original film and TV opportunities. This points to an increasingly active creator-to-studio pipeline.
Amazon continued building creator services around commerce
Amazon’s creator services and creator ad partnership push reflects the same broader theme seen in Chief Media / Reach Social and Whatnot: creator marketing is moving closer to measurable commerce and retail media outcomes.
What this says about the market
The recent activity points to six themes.
Creator media is institutionalizing.
Unwell and Acast / Backyard both show that scaled creator audiences can support real institutional capital and strategic M&A when the business has multiple monetization channels.
Talent representation remains a consolidation market.
DBA / V1sion shows that management rosters and creator relationships remain acquisition targets, especially for larger agencies with centralized sales and operating infrastructure.
Commerce is becoming the premium layer.
Whatnot, Chief Media / AMZ / Reach Social, Amaze / C2 Live and Amazon Creator Services all point in the same direction. Buyers want creator businesses that can connect influence to transactions.
Podcasting is becoming broader than podcasting.
Acast / Backyard and The Podcast Consultant / Rise25 show two versions of the same trend: podcast businesses are increasingly valued for their ability to create repeatable distribution, advertising and relationship infrastructure.
Creator IP is becoming financeable.
IPNation’s MENA music-rights platform reinforces that creator and artist rights can be underwritten as cash-flowing assets with additional upside from active commercialization.
Platforms are competing directly for creator supply.
Disney licensing Dhar Mann content and YouTube reportedly offering exclusivity packages both show that large platforms and media companies increasingly treat creators as premium content suppliers.
The creator economy is still fragmented, but the buyer logic is getting sharper.
The most valuable assets are not simply accounts with large followings. They are businesses with durable audience relationships, proprietary content, measurable monetization, transferable customer relationships and infrastructure that can scale beyond any one personality.
✦ Talk to Stellamont
Thinking about selling your agency, talent management firm, creator business, or media company? We advise founders on valuation, transaction preparation, and competitive sell-side processes across the creator economy.
The Unwell number is the one to sit with. That's not a podcast valuation, it's an audience being priced like a company because it owns IP across audio, video, live, products and brand deals. Most creators are still renting their reach to one platform and calling it a business. The ones getting $500M valuations built the distribution first, then stacked monetization on top of it. Own the audience, own the IP, and the money follows - not the other way round.